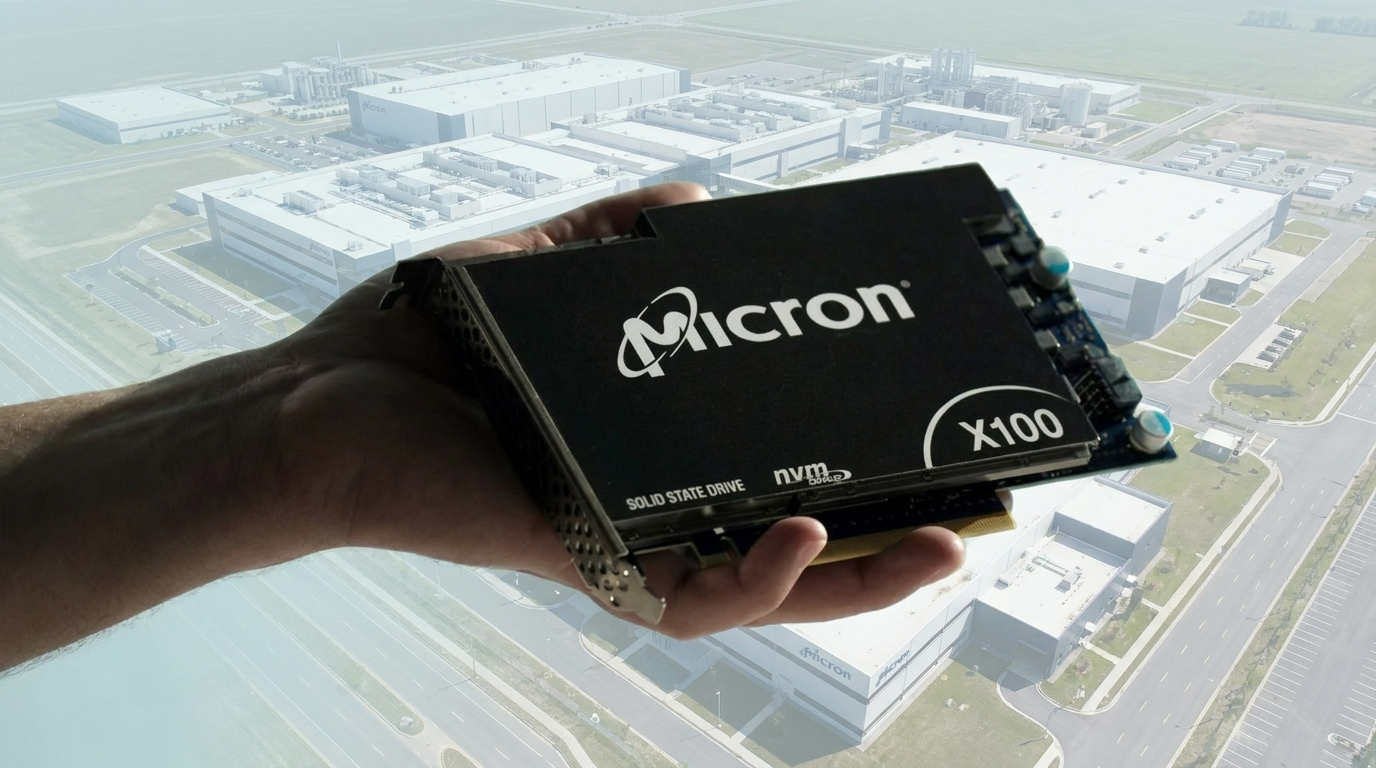
Micron’s first promise to investors is that its extraordinary earnings growth is being driven by structural AI demand rather than a temporary rally in memory prices. Revenue is expected to approach $51 billion for the August quarter, while adjusted earnings could rise from $3.03 per share a year earlier to more than $31, guided by strong pricing and margins. Demand is also broadening beyond GPU-heavy workloads as agentic AI increases the need for CPU memory and system DRAM, giving Micron exposure to more parts and volume of the data center stack. If management maintains strong fiscal 2027 guidance, investors would have stronger evidence that the current earnings gain can endure beyond a single peak quarter.
The Technology Keeping Micron Relevant
Micron’s second promise is that it can remain technologically relevant even while competing against larger HBM suppliers such as SK Hynix and Samsung. Its HBM4 products deliver higher bandwidth, improved energy efficiency, and greater memory capacity, while the company is also expanding into PCIe Gen6 SSDs and SOCAMM2 modules for AI systems. A faster HBM4 production ramp and close integration with platforms such as Nvidia’s Vera Rubin could allow Micron to capture more value from each generation of AI accelerators. Investors therefore need evidence that technological execution, not just tight supply, can support Micron’s margins and future HBM revenue.
The Tight Memory Markets
Micron is also confident that the memory shortage supporting its current profitability will not disappear quickly. The company expects DRAM and NAND demand to remain above supply beyond 2027, while growing AI workloads continue to consume more memory per server and accelerator. That imbalance is central to the company’s exceptional gross margins because constrained supply allows Micron to command higher prices without relying solely on shipment growth. The earnings outlook will matter most if management can show that disciplined industry capacity and AI demand are likely to keep this pricing environment favorable into fiscal 2027.
The Geopolitical Advantage
Micron’s U.S. headquarters and domestic manufacturing strategy give it a position that neither Samsung nor SK Hynix can replicate in exactly the same way. The company is supporting tighter restrictions on Chinese memory competitors while expanding production closer to American semiconductor and data center customers. This positioning could strengthen Micron’s strategy in a market where governments increasingly treat advanced memory as defense critical infrastructure, although retaliation from China and faster Chinese self-sufficiency remain significant risks, especially from CXMT. For investors, the promise is that Micron can convert its American manufacturing footprint and policy alignment into greater supply-chain relevance without sacrificing access to major global markets.
The Capacity to Fund Growth
Micron’s planned U.S. investment of more than $250 billion through 2035 is a commitment to turn current profits into long-term manufacturing capacity. Its New York mega-fab project, CHIPS Act support, and goal of producing a larger share of DRAM in the United States could position the company closer to the world’s largest AI infrastructure customers. The risk is that these projects carry enormous fixed costs if memory prices weaken before the new capacity earns acceptable returns. Investors therefore need Micron to demonstrate that its expansion is paced against durable demand rather than built around assumptions that require today’s unusually strong market conditions to continue indefinitely.
This marketing material is provided for informational purposes only and does not constitute investment advice, a recommendation, or an offer or solicitation to buy or sell any financial instruments.
Trading in securities involves significant risk and may not be suitable for all investors. Prices of securities may fluctuate significantly and may result in a total loss of your investment. Investors should be aware that losses may exceed potential profits when buying and selling securities. In certain market conditions, you may sustain losses that exceed your initial investment. Securities and contracts for differences are complex financial instruments that require a high level of knowledge and understanding. You should carefully consider whether you understand how these instruments work and whether you can afford to take the high risk of losing your money.